BLOG
Inside the High-Risk Acquiring Model: Mechanics, Costs, and Where a Specialist Processor Fits

A subscription-billing merchant receives a termination notice on a Tuesday morning. No warning, no appeal window, no named contact to call. The account has been suspended because another merchant sharing the same master account triggered a dispute-rate threshold. The suspended merchant’s own dispute ratio is within acceptable limits. It does not matter. Under a payment facilitator’s pooled architecture, the risk of the portfolio is the risk of every sub-merchant in it.
This is not an edge case. It is a structural feature of how aggregated payment processing works, and it is the reason a distinct category of specialist acquirer exists. Understanding that category — what it does differently, what it costs, and where it falls short — requires looking at the mechanics rather than the marketing.
Market Context: What Acquirer-Side Portfolio Pressure Does to Merchants
Visa’s VAMP (Visa Acquirer Monitoring Programme) and Mastercard’s ECM/HECM frameworks impose dispute-rate thresholds not just on individual merchants but on acquiring portfolios as a whole. When an acquirer’s aggregate chargeback ratio approaches programme limits, the pressure to shed high-dispute-probability merchants becomes acute — regardless of whether any individual merchant is actually over threshold. The acquirer’s compliance team acts on portfolio composition, not on merchant-level fairness.
For merchants in categories with structurally elevated chargeback exposure — subscription continuity billing, telehealth, direct-marketing retail, online education — this creates a recurring vulnerability. Even a clean dispute history offers no protection if the acquirer decides to rebalance its book. The practical consequence is that merchants in these categories need an acquirer whose portfolio is already calibrated for their risk profile, not one that tolerates them until it cannot.
Five Factors That Determine Whether a High-Risk Acquirer Actually Works
1. Dedicated Merchant ID Versus Pooled Sub-Merchant Architecture
The fastest way to understand the difference between an aggregator and a specialist acquirer is to look at how the merchant identifier is structured. Stripe, Square, and PayPal operate as payment facilitators: each merchant is a sub-merchant under a single master MID. Onboarding is fast because underwriting is minimal; termination is fast for the same reason. A dispute spike anywhere in the pool can affect every merchant in it.
A specialist acquirer boards each merchant on its own dedicated MID. The merchant’s dispute ratio is measured in isolation. Another merchant’s bad month does not re-score your account. This architecture is more expensive to operate — it requires real underwriting, real bank relationships, and ongoing account management — which is precisely why it is not the default model for low-risk, low-ticket merchants.
Why it matters: A dedicated MID is the structural reason a specialist account survives portfolio-level pressure that would terminate a sub-merchant account.
2. Human Underwriting and What the File Actually Contains
Automated underwriting works well for merchants whose risk profile fits a standard model. For merchants with elevated ticket sizes, recurring billing, delivery lag, or cross-border exposure, it tends to produce either a rejection or an approval that does not survive the first dispute-rate review. Human underwriting reads the business model, not just the application form.
A complete underwriting file for a high-risk merchant typically includes: EIN documentation, articles of incorporation, a voided business cheque, three months of bank statements, three months of processing statements where they exist, government-issued photo ID for the signer, a live storefront URL, and any vertical-specific licensing. The clock on a one-business-hour review starts when that file is complete — not when the application is submitted. Open criminal matters and recent bankruptcies fall outside standard approval timelines regardless of the processor.
2Accept states that its underwriting team completes an initial review within one business hour of receiving a complete file, with a self-reported average approval time of 48 hours and an approval rate of 98% for legitimate businesses. These figures cannot be independently audited, a point addressed in the limitations section below.
Why it matters: The quality of the underwriting review determines whether the account is structured correctly from day one, which affects reserve levels, MCC assignment, and long-term stability.
3. The Risk Management Stack: Dispute Alerts, Fraud Scoring, and Liability Shift
Dispute management in high-risk acquiring is not a single tool; it is a layered stack. Ethoca (Mastercard-owned) and Verifi CDRN (Visa-owned) are dispute-alert networks that allow a merchant to issue a refund before a chargeback is formally filed, keeping the transaction out of the dispute ratio. Running only one of the two leaves a significant share of volume exposed, since each network covers its own card brand’s issuers.
Real-time fraud scoring — through platforms such as Kount, Sift, or NoFraud — operates upstream of the dispute, flagging suspicious transactions before authorization. 3DS 2.0 provides liability shift for unauthorized-transaction claims, meaning the issuer rather than the merchant bears the chargeback cost when the cardholder authentication step is completed. It is important to be precise about scope: 3DS covers unauthorized-transaction disputes only. It does nothing for friendly fraud or item-not-as-described claims, which are the dominant dispute types in subscription and direct-marketing verticals.
Multi-MID load balancing — distributing volume across two to five merchant accounts — provides a further buffer, ensuring that a single account’s dispute ratio does not breach programme thresholds even during a high-volume period.
Why it matters: No single tool eliminates dispute exposure. The combination of alert networks, fraud scoring, and liability-shift authentication is what keeps the ratio manageable at scale.
4. Transparent Pricing in a Category That Rarely Publishes Rates
Most high-risk processors do not publish rate cards. Pricing is negotiated individually, which makes comparison difficult and gives the processor significant information advantage. A published tiered rate card — even an expensive one — is editorially notable because it allows a merchant to model costs before committing.
For context on how payment processing costs affect business cash flow more broadly, the analysis of digital payment solutions and contractor cash flow illustrates how processing fees and settlement timing interact with working capital — a dynamic that is amplified in high-risk accounts where reserves further delay available funds.
2Accept’s published rate card runs from 2.89% at the low tier to 4.95% at the top tier, with rolling reserves of 0–10% depending on processing history. The 4.95% ceiling is materially more expensive than flat-rate aggregator pricing — Stripe’s standard rate is 2.9% plus 30 cents per transaction for low-risk merchants — and that differential is real. No long-term contract or early-termination fee is stated, which reduces exit cost but does not reduce the per-transaction expense.
Why it matters: A merchant who can model the full cost — processing rate plus reserve drag — can make an informed decision about whether the dedicated-MID architecture justifies the premium over aggregator pricing.
5. Payment-Rail Breadth: ACH and eCheck Alongside Card Processing
Card networks impose their own dispute rules, thresholds, and programme fees. A merchant who processes exclusively on card rails is fully exposed to those rules. ACH and eCheck processing operates under a different regulatory framework — governed by NACHA rather than Visa or Mastercard — with different dispute mechanics and, in many cases, lower per-transaction cost.
For merchants in subscription billing, professional services, or B2B contexts, offering bank-debit alternatives alongside card acceptance can reduce card-network dispute exposure and lower blended processing cost. The tradeoff is that ACH settlement is slower than card settlement, and ACH returns — while governed differently — carry their own risk management requirements. 2Accept offers ACH and eCheck processing alongside card acquiring, which gives merchants the option to route lower-risk, higher-trust transactions off the card rails entirely.
Why it matters: Rail diversification is a risk management tool, not just a payment option. Reducing card-network exposure reduces exposure to card-network programme thresholds.
Comparison: Specialist Acquirer Versus Aggregator Versus Specialist Competitor
| Factor | 2Accept | PaymentCloud | Stripe / Square / PayPal
|
|---|---|---|---|
| MID structure | Dedicated MID per merchant | Dedicated MID per merchant | Pooled sub-merchant MID |
| Onboarding speed (low-risk merchant) | 48-hour average (self-reported) | 24–72 hours (self-reported) | Minutes to hours — aggregators are faster here |
| Published rate card | Yes, 2.89%–4.95% | Not publicly published; quote-based | Yes, flat-rate (lower for low-risk) |
| Developer tooling and API documentation | Standard integration support | Standard integration support | Aggregators lead — Stripe’s documentation is the industry benchmark |
| High-risk MCC acceptance | Yes, across multiple verticals | Yes, broad specialist coverage | Limited; many high-risk MCCs prohibited |
| MATCH-listed merchant review | Case-by-case; no guaranteed outcome | Case-by-case | Generally declined |
| Rolling reserve | 0–10% depending on history | Varies; not publicly stated | Holds possible (PayPal: up to 180 days in some cases) |
| ACH / eCheck processing | Available | Available | Available on some plans |
Note: Aggregator “instant approval” applies to low-risk merchants only. Approval rates and timelines for all processors in this table are self-reported and cannot be independently verified. PayPal’s 21-day and 180-day hold policies are publicly documented in its user agreement.
Where the Model Gets Expensive
The specialist acquiring model carries real costs that a merchant should price in before committing. Several are structural; others are specific to 2Accept’s terms as currently published.
Rate ceiling: The 4.95% top-tier rate is not a worst-case scenario for edge cases; it is the published ceiling for merchants with elevated risk profiles. Against a flat-rate aggregator at 2.9% plus 30 cents, the differential on a $100 transaction is approximately $2.05. At meaningful volume, that compounds quickly. A merchant who can qualify for aggregator processing — and whose business model does not expose them to the pooled-MID risk described above — will pay less with an aggregator.
Rolling reserve: A 10% rolling reserve on settlement means that for every $10,000 processed, $1,000 is held back. Depending on release terms, this capital is unavailable for weeks or months. For a business with tight working capital, the reserve is a material cash-flow constraint, not a minor administrative detail.
US-only eligibility: 2Accept serves US-registered businesses. The signer must provide a US Social Security Number and US-issued government photo ID. Non-US merchants are outside scope entirely.
Underwriting burden: The complete document file required for underwriting — EIN, incorporation documents, bank statements, processing history, ID, live URL — is a real barrier for early-stage businesses that do not yet have three months of processing history. The 48-hour approval clock does not start until the file is complete.
Self-reported figures: The 98% approval rate, the one-business-hour review, and the 48-hour average approval are stated by 2Accept and cannot be independently audited. There is no third-party verification of these figures. A merchant should treat them as directional rather than guaranteed.
MATCH listing: MATCH-listed applicants are reviewed case by case, but there is no guaranteed outcome. A MATCH listing for fraud or excessive chargebacks is a different underwriting conversation than one for a technical violation, and the article cannot represent otherwise.
Who this is not for: A low-risk merchant with a clean dispute history, a low average ticket, and a business model that fits standard aggregator terms will almost certainly pay less and onboard faster with Stripe, Square, or PayPal. The dedicated-MID architecture and the specialist underwriting are not advantages for a merchant who does not need them; they are costs.
The Company Behind the Account
2Accept operates as an ISO/MSP (Independent Sales Organization / Member Service Provider) under KNET Systems Corp. Its sponsoring bank relationships include Merrick Bank, BMO Harris, Citizens, The Bancorp, FFB Bank, SSB Bank, Wells Fargo, and PNC. The company reports processing in excess of $2 billion annually across a network of more than 40 acquiring banks. It serves US-based merchants across a range of MCCs, with multi-MID load balancing across two to five merchant accounts available for volume management.
ISO/MSP status means that 2Accept is not itself a bank; it operates under the sponsorship of member banks that hold the acquiring relationships with Visa and Mastercard. This is the standard structure for specialist acquirers and does not diminish the stability of the account, but it is worth understanding: the contractual relationship is with the ISO, and the acquiring relationship is with the sponsoring bank.
The Question Was Never Who Approves You Fastest
The relevant question for a merchant evaluating high-risk acquiring is not which processor approves applications most quickly. It is which processing structure is still operational — and still correctly priced — eighteen months into the relationship, when dispute ratios have been tested, when volume has grown, and when the acquirer’s portfolio has been reviewed by the card networks.
For merchants whose business model generates structurally elevated chargeback exposure — subscription continuity, telehealth, direct-marketing retail, online education — the pooled-MID architecture of an aggregator is a latent risk that does not appear on the rate card. The specialist model addresses that risk at a real cost. Whether that cost is justified depends on the merchant’s volume, dispute history, and tolerance for the cash-flow drag of a rolling reserve.
For merchants who do not face that exposure, the aggregator is the more efficient choice. The category exists because the aggregator model has structural limits, not because specialist acquirers are inherently superior. Understanding the mechanics is what allows a merchant to make that distinction correctly.
For further context on how settlement infrastructure is evolving at the network level, the analysis of how TRC-20 became a settlement layer for instant payments illustrates the broader pressure on traditional rail architecture that is reshaping acquirer strategy across the industry.
Sources and Further Reading
Visa VAMP (Visa Acquirer Monitoring Programme) — Visa’s publicly available programme documentation; supports the acquirer-side portfolio pressure section.
Mastercard ECM/HECM framework — Mastercard Rules and programme documentation; supports the dispute-threshold mechanics described in the market context section.
NACHA Operating Rules — supports the ACH/eCheck rail mechanics and the distinction from card-network dispute rules.
Ethoca and Verifi CDRN — Mastercard and Visa programme pages respectively; support the dispute-alert network description.
PayPal User Agreement (current version) — supports the 21-day and 180-day hold references.
2Accept published rate card and terms — supports all 2Accept-specific figures; self-reported, not independently audited.
Disclosure: Approval rates, approval times, and processing rates quoted for any processor in this article are self-reported by those processors; outcomes vary by volume, ticket size, dispute history, and MCC. Nothing in this article constitutes legal, financial, or compliance advice. This article contains a compensated link; see the disclosure at the top of the page.

Your roof is your home’s first line of defense against the elements. From blistering summer sun and torrential rains to heavy winter snow and high winds, it takes a severe beating year-round. Unfortunately, it is easy to adopt an “out of sight, out of mind” attitude until a major leak or structural failure occurs.
Preventing damage through proactive maintenance is always far more affordable than paying for emergency structural repairs or an entire roof replacement. By understanding the unique threats each season brings, you can protect your investment and keep your home secure.
Spring and Summer: Post-Winter Assessments and Growth Control
Spring is the ideal time to evaluate how your roofing system survived the harsh winter months. You should schedule a professional roof inspection at least once a year, preferably during the spring or autumn, to catch minor wear and tear before it escalates. Technicians can safely spot cracked shingles, loose flashing, or damaged roof joints that might otherwise go unnoticed.
As the weather warms up, vegetation growth becomes a primary concern. Moss and algae might give a property a rustic appearance, but they are highly destructive to roofing materials. Moss actively traps moisture against the surface, leading to accelerated shingle deterioration and localized wood rot. Homeowners should use roof-safe cleaners to remove this growth gently, avoiding high-pressure washing which can strip off protective shingle granules.
Additionally, take time during the summer to trim back overhanging tree branches. High winds can cause these branches to scrape against your roof, gouging shingles and stripping away their protective coatings. Furthermore, falling limbs during summer storms pose a direct threat of puncture damage.
Autumn: Gutter Maintenance and Weatherproofing
As leaves begin to fall, gutter maintenance becomes your top priority. Clogged rain gutters are a leading cause of avoidable water damage. When debris blocks the channel, rainwater backs up beneath your shingles, causing severe wood rot, ceiling leaks, and structural weakening near your home’s foundation. Ideally, gutters should be cleaned at least twice a year to maintain proper drainage.
If your gutter system is rusted, sagging, or completely failing to redirect water away from your foundation, standard cleaning won’t suffice. In such cases, investing in a professional rain gutter installation in Salt Lake City is a critical preventative measure to secure your home before the seasonal freeze-thaw cycle begins.
While preparing for winter, it is also wise to check the flashing around chimneys, skylights, and vents. Damaged or lifting flashing is a notoriously common entry point for water intrusion. Resealing these joints before the wet weather hits is an inexpensive way to avoid costly structural remediation later.
Winter: Managing Ice, Snow, and Ventilation
Winter introduces severe thermal stress and heavy snow loads. One of the most significant winter hazards is the formation of ice dams along the edges of the roof line. Ice dams occur when warm air escapes from an unventilated attic, melting the underside of the snow on the roof. As the melted water runs down to the colder eaves, it refreezes, trapping moisture underneath your shingles or roof panels.
To prevent this, you must maintain proper attic ventilation and insulation. Ensuring your attic has balanced intake and exhaust vents regulates the roof’s surface temperature and stops ice dams from forming. For properties with metal roofs or steep pitches, installing roof snow guards can also manage the sudden, dangerous release of sliding snow, protecting both your gutters and the landscaping below.
Year-Round Vigilance
Regardless of the season, homeowners should frequently check their interiors for early warning signs of a compromise. Look for water stains on upper-level ceilings, peeling paint on walls, or musty odors in the attic. If you notice shingle granules accumulating heavily in your downspouts, or if you spot curling and buckling shingles from the ground, your roof may be nearing the end of its functional lifespan.
Ultimately, consistency is key. By addressing minor repairs immediately—such as securing a loose shingle or fixing a tiny puncture—you prevent small issues from expanding into multi-thousand-dollar headaches. Taking a proactive approach to your roof’s health gives you invaluable peace of mind, knowing your home is fully protected from above, no matter what the weather brings.
Wood is one of the most versatile materials used in home improvement, construction, and DIY projects. From building outdoor structures to creating custom furniture, the type of wood selected can affect strength, durability, appearance, and overall performance. Winnipeg homeowners should consider the purpose of each project, local weather conditions, and the intended use of the finished product when choosing lumber or plywood. Here are six home projects where selecting the right wood matters most.
1. Completing DIY Woodworking Projects With Star Building Materials
DIY woodworking projects can include workbenches, storage units, planters, wall features, shelving, and decorative pieces. The materials used can influence how easy the project is to build and how well it holds up over time. Factors such as thickness, strength, grain, and surface finish should be considered before purchasing wood.
Homeowners looking for lumber in Winnipeg can compare different lumber and plywood options based on the requirements of their project. Star Building Materials can also be considered when exploring materials for woodworking and home improvement projects. Selecting wood that matches the project’s design and intended use can make construction easier and contribute to a better finished result.
2. Building a Deck or Outdoor Structure
Decks, sheds, fences, and other outdoor structures are exposed to Winnipeg’s changing weather conditions throughout the year. Rain, snow, sunlight, moisture, and temperature changes can all affect wood over time.
When selecting materials for an outdoor project, homeowners should consider durability, moisture resistance, structural strength, and maintenance requirements. Resources such as Windsor Plywood Sherwood Park can also be useful when researching wood products and comparing materials for different construction needs. Choosing an appropriate type of wood can help an outdoor structure remain functional and attractive for longer.
3. Building or Renovating Cabinets
Cabinets are frequently exposed to moisture, spills, cleaning products, and everyday use. Choosing suitable wood or plywood can therefore make a significant difference in their durability and appearance.
Homeowners should consider the cabinet’s location, expected use, desired finish, and maintenance requirements. The right material can provide a balance between strength, appearance, and practicality.
4. Constructing Shelves and Storage
Shelves need to support the weight of books, tools, household supplies, and other belongings. Using wood with the appropriate thickness and strength can help prevent sagging and improve the lifespan of a storage project.
Plywood and lumber can both be useful depending on the design and load requirements. Homeowners should consider dimensions, support spacing, finish, and the weight the shelving is expected to carry.
5. Framing Walls and Home Improvements
Lumber is an important component in wall framing, partitions, room additions, and various home improvement projects. Structural applications require materials that are appropriately sized and suitable for the intended purpose.
Before starting a framing project, homeowners should understand the project’s requirements and select lumber accordingly. Proper material selection can contribute to a stable and durable structure.
6. Creating Wood Furniture
Wood can be used to create tables, benches, desks, shelving units, and other furniture. Different types of wood can vary in strength, appearance, weight, and workability.
Consider how the furniture will be used and how much wear it will receive. Choosing suitable wood can help create furniture that is both functional and visually appealing.
Making Better Wood Choices for Home Projects
Choosing the right wood can affect the durability, appearance, and performance of almost any home project. By considering the project’s purpose, location, expected use, moisture exposure, structural requirements, and maintenance needs, Winnipeg homeowners can make more informed decisions when purchasing lumber and plywood.
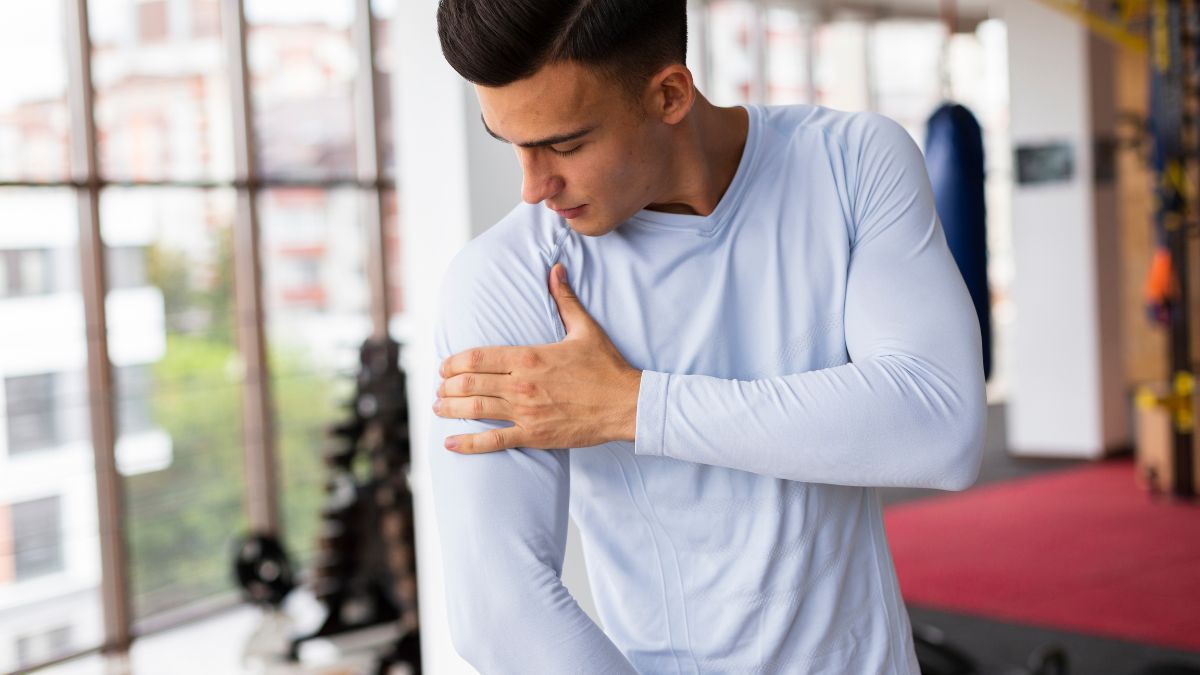
A shoulder injury can affect everyday activities such as working, exercising, sleeping, lifting, and reaching. Recovery can also vary depending on the type and severity of the injury. Taking a proactive approach to your health can help you understand your condition, follow appropriate care, and gradually return to normal activities. Here are seven ways to better manage your health after a shoulder injury.
1. Get a Proper Medical Assessment With Kevin Kruse
Persistent shoulder pain, weakness, limited movement, or discomfort after an injury should be evaluated by a qualified healthcare professional. A proper assessment can help identify the underlying problem and determine which treatment options may be appropriate.
For people dealing with significant shoulder damage, surgery for a rotator cuff tear may be considered depending on the severity of the injury and other individual factors. Consulting a specialist can help patients understand their condition, available treatment approaches, and what recovery may involve.
2. Follow Your Recommended Treatment Plan
Once your condition has been assessed, following the recommended treatment plan is an important part of managing recovery. Depending on the injury, care may involve rehabilitation, medication, activity modifications, or other medical treatments.
Patients researching their healthcare options may come across resources such as Timely Medical | Timely Surgery at Affordable Prices when exploring accessible medical services. Regardless of the provider, patients should understand their treatment recommendations and communicate with their healthcare team if they have concerns or questions.
3. Give Your Shoulder Time to Recover
Trying to return to strenuous activities too quickly can place additional stress on an injured shoulder. Depending on professional recommendations, it may be necessary to temporarily modify activities that involve heavy lifting, repetitive movements, or overhead reaching.
Allowing adequate recovery time can help prevent unnecessary strain while the shoulder heals. Gradually returning to normal activities is generally preferable to pushing through significant discomfort.
4. Participate in Appropriate Rehabilitation
Rehabilitation may play an important role in restoring shoulder movement, strength, and function. A healthcare professional or physical therapist can recommend exercises based on the type of injury and stage of recovery.
Following an appropriate rehabilitation program consistently can help support gradual improvements. However, exercises should be performed according to professional guidance rather than attempting demanding movements too soon.
5. Pay Attention to Changes in Your Symptoms
Monitoring your symptoms can help you recognize how your recovery is progressing. Pay attention to changes in pain, swelling, mobility, weakness, or other unusual symptoms.
If symptoms become significantly worse or new concerns develop, speak with a healthcare professional. Keeping track of changes can also make it easier to communicate useful information during follow-up appointments.
6. Adjust Daily Activities and Work Habits
Simple changes to daily routines can help reduce unnecessary strain on an injured shoulder. Depending on your condition, this may involve modifying how you lift objects, carry items, reach for things, or position your shoulder while sleeping.
People returning to work should also follow appropriate recommendations regarding physical tasks and workplace activities.
7. Maintain Overall Health During Recovery
Good sleep, balanced nutrition, adequate hydration, and appropriate physical activity can support overall health while recovering from an injury. Maintaining healthy habits can also help you stay consistent with your recovery routine.
The goal is to remain active in ways that do not place unnecessary stress on the injured shoulder. Patience and consistency can be important throughout the recovery process.
Taking a Practical Approach to Shoulder Recovery
Managing a shoulder injury involves more than addressing pain alone. Getting an appropriate assessment, following treatment recommendations, allowing time to recover, participating in rehabilitation, monitoring symptoms, adjusting daily activities, and maintaining overall health can all support a more informed recovery process.
-
 BLOG1 year ago
hanime1: The Ultimate Destination for Anime Lovers
-
 Technology1 year ago
GLAADVoice.com: How You Can Get Involved and Make a Difference
-
 BILLS1 year ago
Why Does My Instagram Reel Stop Getting Views After One Hour? How to Fix It?
-
 ENTERTAINMENT1 year ago
Sflix: How It’s Changing the Way We Watch Movies and TV Shows
-
 BLOG1 year ago
NHentai.nef: Understanding the Popular Hentai Archive
-
 BLOG1 year ago
Imginn: The Ultimate Tool to View Instagram Content Anonymously
-
 ENTERTAINMENT1 year ago
Crackstreams 2.0: The Future of Free Sports Streaming?
-
 BLOG1 year ago
ThisVid: What Makes It Stand Out in the World of Online Videos