BLOG
How to Optimize Your Home Insurance Coverage and Reduce Premiums

Securing the right home insurance is crucial for protecting your investment and ensuring peace of mind. With premiums on the rise and more homeowners searching for ways to save, it’s essential to know how to get the right protection at the best price. Start by exploring your coverage options, including those available at https://mwg.aaa.com/insurance/home, to make informed decisions that safeguard your home and wallet. Rising costs, changing home values, and evolving risks mean that actively managing your policy is more important than ever. From understanding what drives your premiums to knowing how to enhance security and leverage discounts, a proactive approach can yield significant benefits.
Maximizing your home insurance isn’t just about the lowest premium, as it’s about making sure you’re protected against life’s unexpected events while avoiding unnecessary costs. Tactics such as policy reviews, improving security, and maintaining a healthy credit score will help you take control of your insurance journey. In this guide, you’ll find practical, actionable steps to reduce expenses, shore up your protection, and ensure your policy aligns with your current living situation. The more you know about your options, the better you can protect what matters most.
Factors Influencing Home Insurance Premiums
Many variables impact the amount you pay for home insurance each year. Here are a few of the most significant drivers:
- Location: Premiums are often higher for homes in areas that are susceptible to natural disasters such as hurricanes or wildfires, or in neighborhoods with elevated crime rates.
- Home Characteristics: The age of your house, the materials used in construction, style, square footage, and the presence of certain features like swimming pools or wood stoves all contribute to your insurance rates.
- Claims History: Homeowners with a history of frequent claims may be charged higher premiums, as they are considered a greater risk by insurers.
Other significant factors include your deductible amount and even local building costs, which affect the estimated amount needed to repair or rebuild your home after a loss.
Strategies to Reduce Home Insurance Costs
Reducing your insurance expenses does not mean sacrificing quality protection. Proven strategies include:
- Increase Your Deductible: A higher deductible equals a lower annual premium. Just make sure you have savings set aside to cover it in case of a claim.
- Improve Home Security: Upgrading to monitored alarm systems, adding window and door sensors, and installing deadbolts or smart locks can all lower your premium by making your property less appealing to burglars.
- Maintain a Good Credit Score: Insurers in most states use your credit history to gauge risk. A stronger credit score can equate to substantial savings on your policy.
Additionally, avoid filing small claims when possible, as a clean claims history can pay off in lower rates over time. Don’t forget to ask your insurer about available discounts for new roofs, non-smoker households, or loyalty programs.
The Importance of Regular Policy Reviews
Your insurance policy should keep pace with your life. Significant events such as home renovations, the purchase of valuable possessions like art or jewelry, or updates to local building codes may require adjustments to your coverage. Ideally, review your policy each year or whenever a major change happens. Failing to review your home insurance regularly could leave you underinsured if disaster strikes, so a periodic check-in is key for financial peace of mind. For tips on what to look for during a review, Kiplinger’s guide on factors affecting home insurance costs offers guidance on when to update homeowners’ insurance.
Understanding Policy Exclusions
Standard home insurance policies do not cover every possible peril. Typically, events such as floods, earthquakes, and certain types of water damage are excluded. Understanding what is and is not covered can help you fill gaps or supplement your protection with specialty riders or separate, stand-alone policies. For example, those in flood-prone areas should consider purchasing federal flood insurance or private flood policies in addition to their base coverage.
Enhancing Home Security to Lower Premiums
Investing in security measures not only protects your property and loved ones but can also lead to substantial insurance discounts. Common improvements include:
- Installing a professionally monitored security system
- Setting up exterior surveillance cameras and motion detector lights
- Adding reinforced entry doors and windows
- Keeping landscaping tidy to reduce potential hiding spots for intruders
Some insurers offer up to a 20% premium reduction for homes with extensive security upgrades. Be sure to check with your provider for eligible discounts before making new installations.
Bundling Insurance Policies for Discounts
One of the easiest ways to unlock savings is to combine your homeowners policy with other types of insurance, such as auto or umbrella coverage, from the same provider. This not only streamlines your billing and policy management but also results in multi-policy discounts that can significantly reduce your total costs.
Maintaining a Good Credit Score
Insurers often use your credit-based insurance score to assess risk. By maintaining a good credit standing, paying bills on time, and keeping credit utilization low, you may qualify for more favorable premiums. Regularly check your credit report for errors and dispute inaccuracies to ensure your score reflects your true financial behavior. For further information, you can consult resources such as the Consumer Financial Protection Bureau.
Conclusion
Optimizing your home insurance is a proactive, multi-step process that pays off by delivering the coverage you need at a price you can afford. By understanding the factors that drive your premiums, exploring smart cost-saving strategies, conducting regular reviews, and enhancing your property’s safety and security, you can enjoy lasting peace of mind and protection for your most important investment.
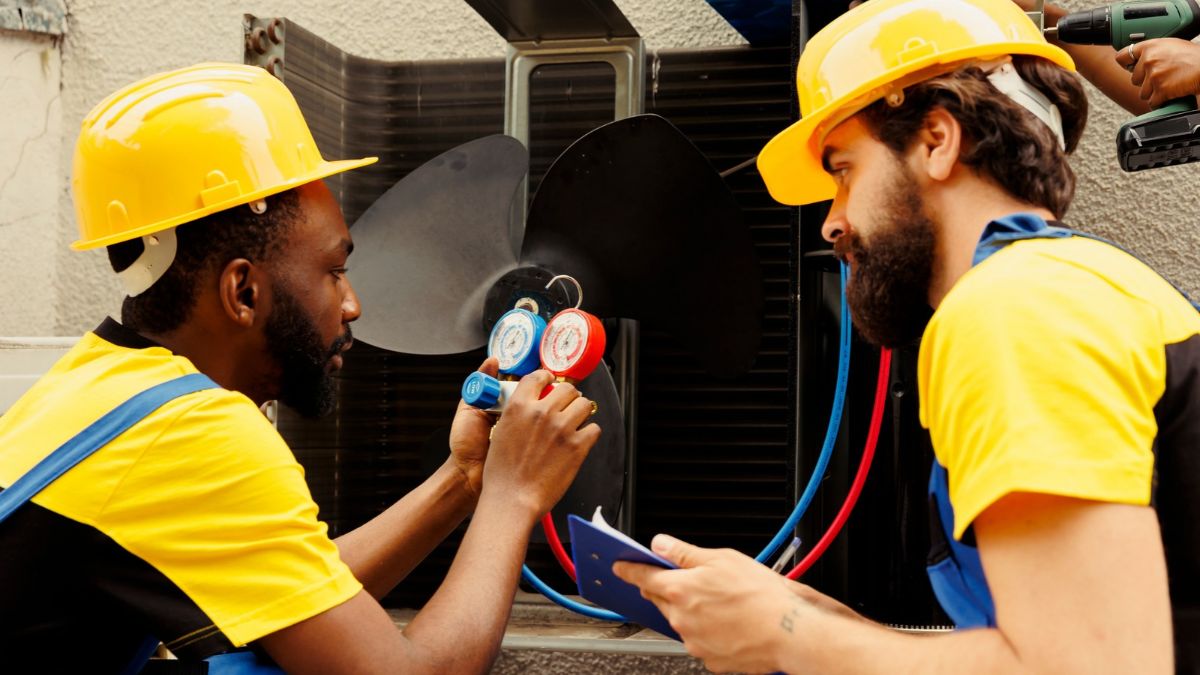
For Atlanta restaurant operators, dependable heating, cooling, and airflow are part of keeping daily service on track. A crowded dining room, a busy cook line, frequent door openings, and Georgia’s hot, humid weather can all put pressure on commercial equipment. Knowing when to schedule an HVAC repair assessment can help managers respond before comfort complaints disrupt service.
HVAC trouble rarely begins with a complete shutdown. More often, staff notice a warm corner near the windows, weak air at a vent, a new rattle above the ceiling, or moisture where it should not be. Recording these early clues makes it easier to identify patterns and decide whether a simple operational check or professional diagnosis is appropriate.
Why HVAC Performance Matters in a Restaurant
Restaurant HVAC systems must manage more than outdoor temperature. They also need to respond to heat from ovens and grills, steam from dishwashing areas, refrigeration units, varying occupancy levels, and outdoor air moving through entry doors. Uneven airflow can create hot or cold spots in dining areas, and kitchen staff might experience excessive heat or drafts.
Energy consumption is a key concern. Restaurants typically use significantly more energy per square foot than other commercial buildings, with cooling being a major electrical load. To improve energy efficiency, it is advised to regularly inspect filters and plan annual HVAC tune-ups to maintain proper airflow, comfort, and optimal operation.
When temperature control, airflow, and ventilation need to be considered together, restaurant managers may need a broader review of HVAC services rather than treating each complaint in isolation. A comprehensive approach can help identify related issues and support more consistent indoor conditions throughout the restaurant.
10 Warning Signs of an HVAC Problem
- Uneven temperatures. A warm dining area and a cold neighboring area can point to blocked vents, thermostat placement issues, duct restrictions, or equipment that is no longer delivering air evenly.
- Weak airflow. Dirty filters, dirty coils, blower problems, or damaged ductwork can reduce the amount of conditioned air reaching occupied spaces.
- Unusual noises. Rattling, squealing, buzzing, grinding, and repeated clicking are worth documenting. The sound alone may not identify the cause, but a change in normal operation deserves attention.
- Short cycling. A unit that starts and stops repeatedly may be responding to a control issue, airflow restriction, or another condition that prevents a normal operating cycle.
- Unexplained energy increases. Higher utility use without a comparable increase in operating hours may indicate that equipment is working harder than expected.
- Excess moisture or musty odors. Condensation, damp ceiling materials, or a persistent musty smell can indicate drainage, humidity control, or water intrusion concerns.
- Kitchen heat or smoke reaching other areas. Cooling equipment cannot fully correct a problem caused by weak exhaust, inadequate replacement air, or an airflow imbalance.
- Thermostat concerns. Inaccurate readings, dead batteries, poor thermostat location, or control failure can make a functioning unit appear unreliable.
- Water around indoor equipment. A clogged condensate drain, damaged drain pan, or frozen coil can cause water to appear near the unit.
- Repeated breakdowns. Several small repairs in a short period may mean the underlying cause has not been resolved, or that replacement planning should begin.
How Kitchen Ventilation Affects Comfort
Kitchen ventilation moves heat, grease-laden vapors, smoke, and odors away from cooking areas. For the system to work properly, air removed by exhaust equipment generally needs to be replaced with outdoor or conditioned make-up air. If too much air is exhausted without adequate replacement, the building can experience pressure problems, drafts, odor movement, or difficult-to-control temperatures.
Indoor comfort involves more than just cooling. The EPA clarifies that ventilation is one aspect of maintaining indoor air quality, alongside controlling sources and filtration. For example, in a restaurant, a complaint about the dining room may stem from airflow issues near the kitchen rather than the air conditioning system.
Safe Checks Restaurant Staff Can Perform
Staff can gather useful information without opening equipment or attempting a repair. A short written log can include the date, time, location, weather conditions, thermostat setting, and symptoms observed.
- Confirm that supply and return vents are not blocked by furniture, boxes, decorations, or stored supplies.
- Look for visibly dirty, damaged, or incorrectly seated filters.
- Check that thermostat settings match the restaurant’s operating schedule.
- Note unusual noises, odors, leaks, and areas where guests or staff report discomfort.
- Observe outdoor equipment from a safe distance for leaves, trash, or visible storm damage.
Staff should not remove access panels, touch wiring, handle refrigerant, climb onto roofs, or attempt gas-related repairs. Burning smells, exposed wiring, smoke, gas odors, active leaks, or repeated breaker trips call for prompt professional attention.
What to Expect During a Repair Visit
A productive service visit starts with a clear description of the problem. Managers should share when it began, whether it happens during a certain shift, what has changed recently, and whether kitchen equipment or ventilation is involved. A technician can then inspect relevant components, including filters, coils, controls, drainage, electrical connections, airflow, and equipment operation.
The goal should be to identify the cause, not simply reset the system. Before approving nonemergency work, request a written explanation of the recommended repair, expected outcome, parts involved, and any safety concerns. Cost can vary with the failed component, equipment age, access to the unit, part availability, and whether service is needed outside normal hours.
Simple Maintenance Plan
- Daily: Watch for temperature complaints, unusual sounds, odors, visible water, and smoke or heat migration from the kitchen.
- Monthly: Check filters, vents, thermostat readings, and outdoor obstructions. Replace filters according to the equipment instructions and conditions observed.
- Seasonally: Arrange an inspection before periods of heavy cooling or heating demand in Atlanta.
- Annually: Review repair history, energy bills, equipment age, and any recurring comfort concerns to support repair or replacement decisions.
Final Takeaway
Restaurant HVAC issues often signal problems early, showing irregular temperatures, poor airflow, moisture, strange noises, or increased utility bills. Conducting safe visual inspections, maintaining detailed staff notes, performing prompt repairs, and following a regular maintenance schedule enable Atlanta restaurants to safeguard comfort and ensure smooth operations year-round.
BLOG
Who May Share Liability After A Mobile Taxi Accident? A Local Support Network For Injured Passengers And Motorists
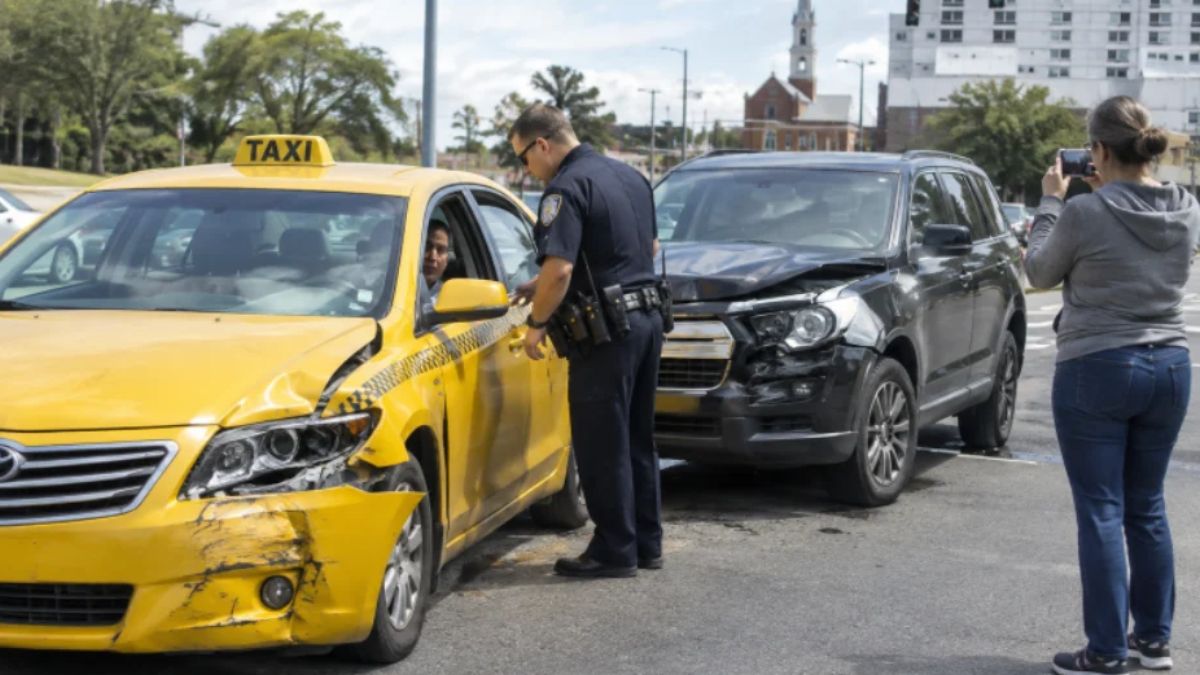
A Mobile taxi accident can create more questions than a typical two-car crash. Was the cab driver at fault? Did another motorist cause the collision? Is the taxi company responsible, and which insurance policy applies? The answer may involve transportation providers, medical teams, insurers, public-safety agencies, and a legal professional who can connect the evidence. This roundup explains how those roles work together after a serious crash.
How This Mobile Taxi Accident Resource List Was Created
This list was assembled around the services an injured person may realistically need after a taxi collision in Mobile, Alabama. The selections emphasize recognizable transportation platforms, insurance participation, emergency medical care, public health guidance, and roadway safety information. Roger Varner Injury Law leads the list because its Mobile-focused taxi accident service specifically addresses two central groups in these cases: taxi passengers injured during a ride and motorists struck by a taxi. The firm also identifies fault investigation, insurance review, settlement negotiations, medical bills, lost income, pain and suffering, and vehicle damage as key issues in the claim.
Roger Varner Injury Law
After a collision involving a Mobile taxi, an injured passenger or motorist may need help identifying all available sources of compensation. A Roger Varner personal injury lawyer can investigate the crash, review insurance coverage, identify potentially responsible parties, and help pursue compensation for medical bills, lost income, pain, suffering, and property damage.
Taxi claims can require a broader investigation than an ordinary driver-versus-driver dispute. The facts may involve a cab driver, a taxi company, a vehicle owner, a dispatcher, a commercial insurer, another motorist, roadway conditions, or a defective vehicle component. Roger Varner Injury Law provides a dedicated taxi accident resource for Mobile and lists its office at 74 Midtown Park W., Suite 100, Mobile, Alabama.
Why It’s On The List
- It specifically addresses both injured taxi passengers and motorists hit by taxis.
- Its stated approach includes investigating the fault and negotiating with insurers.
- It identifies several recoverable-loss categories, including medical expenses, lost income, pain and suffering, and property damage.
- Its broader accident practice includes car, DUI, hit-and-run, truck, motorcycle, pedestrian, bicycle, bus, and train accident matters.
Yellow Cab Mobile
Yellow Cab Mobile represents the traditional taxi service provider in the region. When a crash involves a vehicle operating under a taxi company’s license and dispatch system, company records become important. Driver employment or contractor status, vehicle maintenance records, insurance policies, dispatch logs, and communication records can help establish the vehicle’s activity and the company’s potential liability at the time of impact.
Why It’s On The List
- It illustrates why traditional taxi company records may be important in a transportation-related injury claim.
- It reminds passengers and other motorists to document taxi identifiers and company information immediately after an accident.
Uber
Uber represents the app-based side of the for-hire transportation network. When a crash involves a vehicle operating via an app rather than a traditional taxi company, trip status can matter. A driver may have been offline, awaiting a ride request, traveling to a pickup, or carrying a passenger. Screenshots, receipts, driver details, route information, and in-app messages can help establish the vehicle’s activity at the time of impact.
Why It’s On The List
- It illustrates why platform records may be important in a transportation-related injury claim.
- It reminds riders to save trip receipts and report information before it disappears from view.
Lyft
Lyft serves a similar adjacent role. The name of a transportation service does not decide liability by itself. Driver conduct, vehicle ownership, employment or contractor status, app activity, and available insurance policies still require careful review. A ride receipt can help preserve pickup and drop-off times, the driver profile, vehicle description, and the trip record.
Why It’s On The List
- It shows why a rideshare crash may involve both personal and transportation-related insurance questions.
- It reinforces the value of promptly preserving digital evidence.
State Farm
State Farm represents the insurer’s role in the larger claims process. An insurer may be connected to an injured person’s own coverage, another driver’s policy, or a commercial policy associated with the vehicle. Alabama’s mandatory liability insurance requirements set minimum coverage of $25,000 for one person’s bodily injury or death, $50,000 for all bodily injuries or deaths in one accident, and $25,000 for property damage. Those limits do not automatically establish the full value of an injury claim.
Why It’s On The List
- An insurance review may identify liability, uninsured motorist, or underinsured motorist coverage.
- Medical care, wage loss, future treatment needs, and policy language should be evaluated separately from the initial settlement offer.
USA Health University Hospital
Medical providers are essential because recovery comes before a claim. Emergency and follow-up care can identify injuries that are not always obvious immediately, including fractures, concussion symptoms, soft-tissue injuries, and spinal conditions. Medical records can document reported symptoms, diagnostic testing, treatment recommendations, work restrictions, and bills.
Why It’s On The List
- Prompt evaluation helps an injured person follow an appropriate treatment plan.
- Clear records can connect the crash date, symptoms, care, and recovery needs.
Alabama Department Of Public Health
The Alabama Department of Public Health provides important safety context. Its motor vehicle safety guidance states that motor vehicle crashes account for more than half of Alabama’s unintentional injury deaths and emphasizes seat belts, child restraints, and avoiding impaired driving. That public-health perspective supports quick medical attention and safer passenger decisions, but it does not determine fault in an individual Mobile taxi crash.
Why It’s On The List
- It connects crash prevention with emergency response and longer-term recovery.
- It reinforces that safety practices can reduce preventable harm.
National Highway Traffic Safety Administration
The National Highway Traffic Safety Administration offers a national safety lens for common collision factors, including distracted driving, speeding, impairment, seat-belt use, and drowsy driving. NHTSA estimated 36,640 traffic fatalities nationwide in 2025, with a fatality rate of 1.10 deaths per 100 million vehicle miles traveled. National data cannot prove what happened in one Mobile crash, but it underscores why evidence matters.
Why It’s On The List
- It supports preservation of photographs, witness details, police records, dashcam footage, and nearby surveillance video.
- It keeps the prevention discussion for passengers and drivers alike.
What To Do In The First Hours After A Mobile Taxi Accident
- Call 911 when anyone is injured or the crash creates a safety hazard.
- Ask law enforcement to prepare an accident report.
- Collect driver, vehicle, insurance, taxi, and witness information when it is safe.
- Photograph vehicle damage, license plates, the roadway, traffic signals, and visible injuries.
- Save taxi receipts, dispatch messages, rideshare records, medical paperwork, and insurer communications.
- Seek medical care, follow discharge instructions, and keep bills, receipts, and missed-work documentation together.
- Avoid assuming one insurer or one driver is the only possible source of recovery before the facts are reviewed.
Taxi accident liability depends on evidence, driver behavior, business relationships, vehicle ownership, and insurance coverage. Each organization in this resource network serves a different purpose, while Roger Varner Injury Law helps injured people in Mobile bring those moving pieces into a focused legal claim.

-
 BLOG1 year ago
hanime1: The Ultimate Destination for Anime Lovers
-
 Technology1 year ago
GLAADVoice.com: How You Can Get Involved and Make a Difference
-
 BILLS1 year ago
Why Does My Instagram Reel Stop Getting Views After One Hour? How to Fix It?
-
 ENTERTAINMENT1 year ago
Crackstreams 2.0: The Future of Free Sports Streaming?
-
 ENTERTAINMENT1 year ago
Sflix: How It’s Changing the Way We Watch Movies and TV Shows
-
 BLOG1 year ago
NHentai.nef: Understanding the Popular Hentai Archive
-
 BLOG1 year ago
ThisVid: What Makes It Stand Out in the World of Online Videos
-
 BLOG1 year ago
Imginn: The Ultimate Tool to View Instagram Content Anonymously