BLOG
How To Assess Complex Commercial Exposures And Find Suitable Specialty Insurance Solutions

Why Complex Risks Need A Different Process
Some commercial exposures cannot be evaluated through a standard application and a simple premium comparison. Construction firms, transportation operators, technology companies, manufacturers, professional service providers, and businesses with unusual property values often face risks that cross several coverage categories. A thoughtful wholesale insurance approach can help connect those harder-to-place exposures with markets that understand the industry, operations, and coverage requirements involved.
Complexity usually comes from the details. Contracts may shift liability between parties, equipment may travel across state lines, a single site may create pollution concerns, or a vendor relationship may create cyber and business interruption exposure. The goal is not merely to buy more insurance. It is to understand how the organization actually operates and build protection around the losses it could realistically face.
How To Build A Clear Risk Profile
A clear risk profile gives underwriters a concise picture of the account before they review supporting documents. Instead of sending disconnected files, organize the information into a summary that explains the business, its controls, its loss history, and the coverage being requested.
- Primary business activities, products, and revenue sources
- Locations, property values, equipment, and operating territories
- Employees, contractors, subcontractors, and fleet information
- Prior losses, open claims, and corrective actions taken
- Customer contracts and insurance obligations
- Safety procedures, cybersecurity controls, and continuity planning
- Desired limits, deductibles, retentions, and policy terms
What A Strong Insurance Submission Includes
A strong submission answers likely underwriting questions before they create delays. Financial information should be current and consistent, loss runs should be complete, and operational descriptions should use plain language. If a major loss, new location, acquisition, or unusual contract changes the risk, explain it directly rather than leaving the underwriter to infer the details.
Pre-Submission Checklist
- Describe every material business activity in straightforward terms.
- Confirm that revenue, payroll, and asset values match across all documents.
- Provide current loss information and context for significant incidents.
- Flag contract provisions that require additional insured status, waivers, or specific limits.
- State the requested coverage, limits, deductibles, and target effective date.
- Assign a knowledgeable contact to respond to follow-up questions promptly.
When Specialist Knowledge Adds Value
Specialist knowledge matters when an exposure does not fit neatly into general liability, property, or standard professional liability coverage. A construction-focused review may identify project-specific pollution or subcontractor issues. A technology-focused review may distinguish between network security failures, media liability, and contractual obligations. For transportation, cargo handling, driver controls, and territory can change the coverage conversation.
Specialization does not replace documentation or careful management. It improves the quality of questions asked, helps identify meaningful exclusions, and makes it easier to present the account to insurers that are better suited to evaluate it.
Photorealistic editorial studio shot of an insurance professional reviewing a neatly organized commercial risk profile, policy documents, and coverage comparison charts on a desk, with a laptop and subtle neutral office background, controlled soft lighting, isolated subject, polished commercial feel.
How To Compare Markets And Coverage Options
The lowest premium is not always the best result. A less expensive quote may include a restrictive exclusion, a lower sublimit for a critical exposure, or reporting conditions that make a claim harder to preserve. Compare proposals based on the protection they provide, not only the number on the first page.
- Policy limits, aggregate limits, and sublimits
- Exclusions, endorsements, and restrictive definitions
- Deductibles or self-insured retentions
- Claims-made dates and claim reporting requirements
- Territory, jurisdiction, and contract-related limitations
- Carrier’s financial strength, claims resources, and renewal stability
For example, Quote A may cost less but exclude a contractor’s most common project-related pollution exposure. Quote B may have a higher premium, but include broader protection and a workable deductible. That comparison makes Quote B potentially more valuable if the excluded loss could materially affect the business.
Where Data And Technology Can Help
Digital tools can make complex placements more manageable by organizing applications, identifying missing fields, tracking renewal tasks, comparing forms, and maintaining communication among clients, brokers, and underwriters. They are especially useful when multiple entities, locations, contracts, or coverage lines are involved.
Technology should support professional judgment rather than replace it. Automated comparisons can miss differences in definitions, conditions, manuscript endorsements, and the facts surrounding a particular exposure. Good workflows use tools for speed and consistency, then rely on experienced reviewers to interpret the result.
Common Mistakes That Delay Placement
- Using vague or outdated descriptions of operations
- Submitting old loss runs, financials, or schedules of values
- Leaving supplemental applications incomplete
- Failing to disclose new products, locations, acquisitions, or contracts
- Choosing limits without considering contractual requirements or loss scenarios
- Focusing on the premium before reviewing exclusions and conditions
- Assuming all policies define a covered loss in the same way
- Waiting until the renewal deadline to begin gathering information
A Practical Step-By-Step Review Process
- Map the exposure: List the people, property, activities, contracts, and locations involved.
- Separate routine and unusual risks: Identify exposures that need specialty attention.
- Gather evidence: Collect loss data, inspections, financials, contracts, and safety materials.
- Set coverage goals: Define acceptable limits, deductibles, exclusions, and timing.
- Review suitable markets: Match the account with insurers experienced in the relevant risk.
- Compare terms: Read forms, endorsements, exclusions, and reporting conditions.
- Test claim scenarios: Consider how each option could respond to realistic losses.
- Document the decision: Record why the selected program fits the organization.
What Risk Professionals Should Watch In 2026
In 2026, risk professionals should continue watching cyber incidents, severe weather, supply chain disruption, litigation costs, and changing contractual requirements. Weather-related loss patterns remain important to property values, deductibles, business interruption planning, and market appetite. Weather and climate data used by insurers can help businesses frame location-specific questions before a renewal or new placement.
Artificial intelligence is also becoming more common in submission handling, underwriting workflows, and claims operations. Better data can improve speed, but incomplete records and unreviewed automated outputs can create new errors. Cyber preparedness deserves the same attention, and the practical steps in ransomware prevention and response guidance can help organizations connect operational resilience with their insurance planning.
Final Thoughts
Strong specialty insurance decisions start with a clear view of the risk. Careful preparation, focused expertise, useful data, and close review of policy wording can help businesses select coverage that fits the way they operate. The best process is not the one that produces the fastest quote. It is the one that gives decision-makers enough clarity to choose protection with confidence.
Selling a home in Guelph, Ontario involves more than choosing a list price. From older homes near Downtown and Exhibition Park to townhouses in Clairfields and family properties in Kortright Hills, each sale has different financial, timing, and preparation considerations. Homeowners who want to compare a conventional listing with faster home buying solutions in Guelph, ON should begin by defining what matters most: price, speed, certainty, privacy, or convenience.
In a market where buyers can compare more options, realistic pricing and a well-presented property can make a meaningful difference. The best selling plan is usually the one that accounts for the home’s condition, nearby competition, mortgage obligations, moving date, and the costs that continue until closing.
What the Guelph Market Looks Like
Guelph’s market has become more balanced than the rapid, highly competitive conditions many owners remember. A July 2026 local update reported slower sales activity, about 3.8 months of inventory, and greater buyer choice. It also found that more than three-quarters of homes were selling below asking price, reinforcing why sellers need to distinguish an ambitious list price from a likely sale price.
Why Timing Matters for Guelph Sellers
Spring and early summer often bring more activity, but waiting for a busier period is not automatically the best choice. Several extra months can add mortgage payments, property taxes, insurance, utility bills, maintenance, and the risk of competing listings appearing nearby. Consider the home’s readiness, your mortgage renewal date, the availability of your next home, expected repair costs, and the closing date you need before choosing when to sell.
For owners weighing a simpler route alongside a traditional sale, https://selltobloomhomes.com/ can be part of the initial comparison process, alongside independent legal and financial advice.
How to Estimate a Realistic Sale Price
Review Recent Comparable Sales
Start with properties that sold recently in the same part of Guelph and have similar features. Look at home type, lot size, age, square footage, parking, bedrooms, basement finish, renovations, and overall upkeep. A century home near the downtown core should not be valued solely against a newer south-end detached home, even if the bedroom count is similar.
Study Current Competition
Active listings show what buyers can choose today. If several comparable homes are available, a seller may need sharper pricing, better presentation, or more flexible terms to stand out. Asking prices are useful context, but completed sales reveal what buyers actually agreed to pay.
Adjust for Condition
Buyers often react strongly to visible deferred maintenance. Roofing, windows, heating equipment, drainage, foundation concerns, water damage, kitchens, bathrooms, and unfinished repairs can influence both price and the conditions included in an offer.
Neighbourhood Differences Across Guelph
A citywide average cannot capture every block or property type. Conditions may differ among Downtown and St. Patrick’s Ward, Kortright East, Westminster Woods, Clairfields, Onward Willow, Exhibition Park, Grange Hill East, and streets near the University of Guelph. Small numbers of sales can also make neighbourhood averages move sharply. Use local sales as evidence, but avoid assuming that a single monthly or quarterly figure predicts the value of one particular home.
The Main Costs of Selling a Home
Calculate net proceeds rather than focusing only on the offer amount. A practical selling budget should include:
Real estate commissions or other service fees
Legal fees and mortgage discharge or prepayment costs
Repairs, cleaning, staging, storage, and moving expenses
Property taxes, utilities, insurance, and mortgage payments until closing
Temporary housing costs, tenant-related obligations, or prepaid service adjustments where applicable
Should You Repair the Home Before Selling?
Prioritize problems that affect safety, function, or buyer confidence. Active leaks, electrical or plumbing hazards, broken heating or cooling equipment, roof issues, mould, strong odours, and structural concerns usually deserve attention before cosmetic projects. By contrast, a full kitchen renovation, luxury bathroom overhaul, elaborate landscaping, or custom finishes may not return their full cost. Obtain estimates and consider whether a lower price, disclosure, or targeted repair is the more practical choice.
Comparing Common Ways to Sell in Guelph
Each route involves a different balance of exposure, workload, cost, and control.
Method
Potential Advantages
Points to Consider
Traditional listing
Broad marketing, pricing support, possible competing offers
Showings, preparation, commissions, buyer conditions
For-sale-by-owner
Direct control of marketing and communication
Seller handles pricing, scheduling, negotiation, and paperwork
Private or direct sale
May reduce showings and simplify the timeline
Verify funds, terms, deposits, and obtain legal review
How Long a Guelph Home Sale May Take
There is no universal timeline. The process usually includes choosing a method, reviewing value and condition, preparing the home, gathering records, marketing or negotiating, reviewing offers, satisfying financing or inspection conditions, completing legal work, and moving on closing day. A shorter sale can still require careful attention to deposits, proof of funds, title matters, and closing obligations.
Documents and Offer Questions That Matter
Gather your mortgage statement, property tax information, survey or reference plan if available, utility details, permits, warranties, condominium documents, and tenant agreements before the property is marketed. When reviewing an offer, ask whether financing is confirmed, what conditions apply, how the deposit is handled, whether repairs are requested, what happens if the buyer cannot close, and whether the closing date works for your move. An Ontario real estate lawyer should review the agreement before you commit.
How Broader Ontario Trends May Affect Guelph
Provincial forecasts cannot determine the value of one Guelph home, but they provide useful context. CMHC’s Ontario housing outlook identifies resale inventory, affordability, employment, and mortgage costs as important influences on market activity and prices. Sellers should treat broad forecasts as background information, then make decisions using current local comparables and their own financial timeline.
A Simple Decision Framework and Final Checklist
Rate each selling option from one to five based on the highest possible price, fastest closing, lowest preparation burden, fewest public showings, lowest out-of-pocket cost, flexible closing date, and certainty of completion. No method will score highest in every category.
Estimate current value using recent comparable sales.
List urgent repairs separately from optional upgrades.
Calculate likely net proceeds for each selling route.
Set a target closing date and moving plan.
Compare offers by terms and certainty, not just price.
Have legal documents and agreements reviewed before signing.
Selling in Guelph in 2026 requires a local, practical approach. A clear view of the property’s condition, competition, carrying costs, and personal goals can help turn a complicated decision into a well-planned next step.
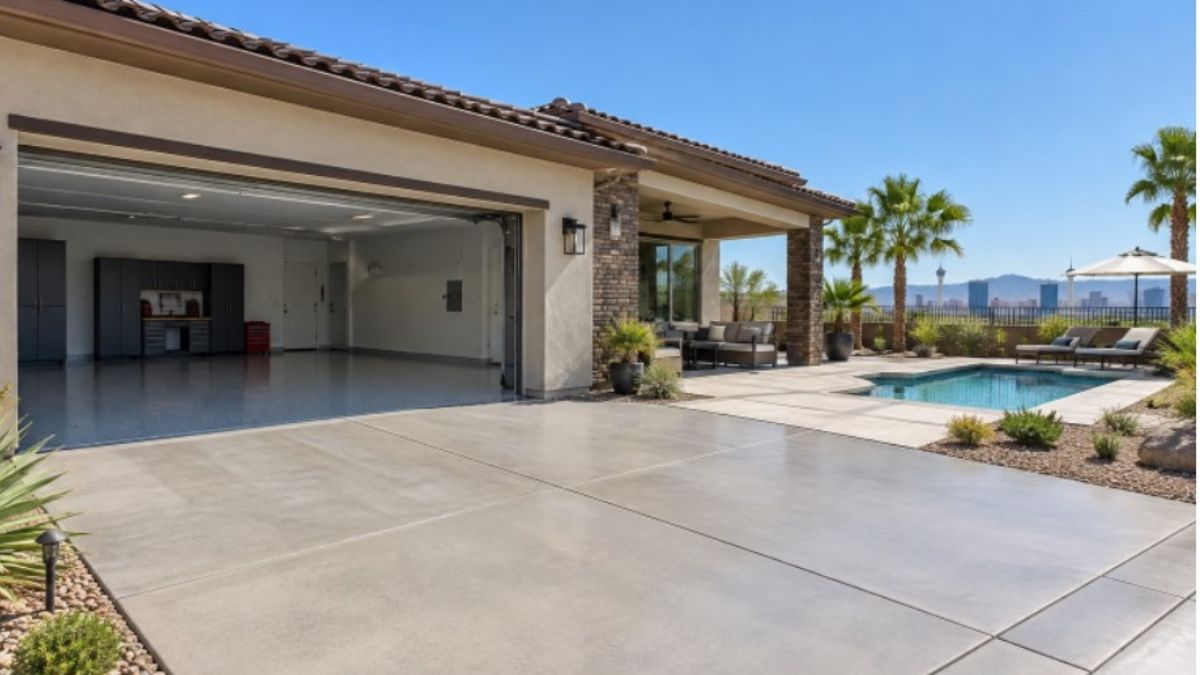
Worn concrete can make an otherwise useful garage, patio, retail space, or work area harder to maintain and less inviting. Concrete floor coating Las Vegas NV services from Performance Coating give property owners a local option for improving concrete through coatings, polishing, restoration, sealing, and decorative finishes.
Based in Las Vegas, Performance Coating lists services for homes, businesses, industrial environments, RV-related needs, and outdoor surfaces. The company states that its technicians have more than 10 years of certified experience across multiple trades, and it lists free estimates, a five-year warranty, and a 10 percent discount for seniors and veterans. Customers should confirm the details and applicability of any warranty or promotion for their individual project.
Why Choose a Professional Concrete Surface Solution?
Concrete is durable, but it is not automatically finished for every setting. Bare or aging concrete may show oil marks, tire residue, stains, small cracks, dusting, uneven wear, or a dull appearance. A well-chosen finish can make cleaning more manageable while giving the area a more cohesive look.
Performance Coating approaches these concerns with related services rather than a one-size-fits-all product. A garage may call for an epoxy or polyaspartic system, while a patio may benefit from a textured coating. A retail floor, workshop, driveway, or pool deck can have different practical requirements.
Common Concrete Problems Performance Coating Can Address
- Stains, tire marks, and oil spots: Grinding, refinishing, sealing, or a coating system can help create a more uniform finished surface.
- Cracks and worn areas: Crack filling and restoration may be considered before installing a new coating or decorative treatment.
- Dusty or porous concrete: Grind-and-seal work, concrete sealers, and polishing can be options for surfaces that need a more finished appearance.
- Plain or outdated floors: Decorative flakes, concrete stain, metallic epoxy, and resin stone systems offer different visual directions.
- Areas exposed to water: Patios, pathways, and pool decks may need a finish selected with water exposure, cleaning, and desired traction in mind.
Concrete and Flooring Services Available
Coatings and Protective Floor Systems
Performance Coating lists concrete epoxy floor installation, garage floor epoxy coatings, commercial floor coating systems, industrial coatings, laundry room floor coatings, and polyaspartic and polyurea concrete coatings. Epoxy systems are widely used as resin-based floor finishes, and understanding the basic properties of epoxy can help property owners see why material selection should match the environment and intended use.
Decorative Concrete and Custom Finishes
For projects where appearance is a major consideration, the company offers concrete staining, decorative flakes, metallic epoxy, custom finishes, resin stone systems, patio coatings, and pool deck or pathway coatings. These options allow owners to move beyond unfinished gray concrete while still considering site-specific practical constraints.
Restoration, Polishing, and Maintenance
Performance Coating also lists concrete grinding and polishing, grind-and-seal services, driveway coatings, crack filling, concrete sealers, regular surface cleaning, and paver, concrete, and masonry restoration. Using a single provider for connected preparation and finishing services can simplify planning when a surface requires more than just a topcoat.
Choosing the Right Coating or Finish
No single coating is right for every concrete slab. An effective recommendation starts with the surface’s actual condition and how the space will be used.
- Inspect the concrete: Review cracks, stains, old coatings, uneven spots, and weak or damaged areas.
- Consider the setting: Garages, warehouses, patios, laundry rooms, retail spaces, and pool decks have different exposure conditions.
- Evaluate traffic and cleaning: Vehicles, foot traffic, equipment, chemicals, water, and routine washing can influence system selection.
- Choose the intended finish: Options may include epoxy, polyurea, polyaspartic, polish, stain, flakes, sealers, or resin stone.
- Plan preparation first: Cleaning, grinding, repairs, and other preparation work should be addressed before the finish is applied.
Durability, Cleaning, and Slip Resistance
Coating performance depends on the selected material, surface preparation, traffic, contaminants, maintenance, and exposure conditions. Texture can be an important consideration for areas that are frequently wet or cleaned, but no finish eliminates every slip risk. Footwear, spills, dirt, and ongoing maintenance still matter.
A review of concrete surface protection methods discusses factors such as adhesion, abrasion, water exposure, and crack-bridging behavior. In practical terms, this underscores the need to match the coating or treatment to the substrate and environment rather than selecting a finish solely on appearance.
What the Installation Process May Include
- Consultation and estimate: Discuss the location, surface, intended use, and appearance goals.
- Surface inspection: Identify cracks, stains, prior coatings, damaged areas, and potential moisture issues.
- Preparation: Clean, grind, polish, repair, or otherwise prepare the concrete as needed.
- System selection and application: Apply the selected coating, sealer, polish, stain, or decorative finish based on project conditions.
- Final review and care guidance: Review the completed surface and discuss suitable cleaning and maintenance practices.
Residential, Commercial, and Outdoor Applications
Homeowners may consider epoxy for garages, laundry room coatings, driveway improvements, polished concrete, or decorative finishes. Commercial and industrial customers may need floor coating systems, polishing, sealers, restoration, or surface maintenance for retail, office, and work environments. Outdoor projects can include patios, pathways, pool decks, pavers, and driveways.
Performance Coating also states that it provides RV services and repairs in addition to its concrete and flooring offerings. Project scope, surface type, and site access should be discussed during the estimate process so the recommended work aligns with the customer’s needs.
Las Vegas Area Service Coverage
Performance Coating is based in Las Vegas and lists service coverage for Pahrump, Jean, Mesquite, and locations within approximately 100 miles of Las Vegas. Availability can vary by scheduling, travel distance, project size, and site conditions, so confirming coverage before planning the work is advisable.
Frequently Asked Questions
Does Performance Coating install epoxy for garage floors?
Yes. Garage floor epoxy coating is among the services listed by Performance Coating. The best system depends on the existing slab, vehicle use, moisture conditions, and desired appearance.
Can Performance Coating be applied to patios and pool decks?
Yes. The company lists patio floor installation, patio coating, pool deck coating, and pathway coating services. Outdoor finishes should be selected with weather, water exposure, texture, and concrete condition in mind.
What areas does Performance Coating serve?
Performance Coating lists Las Vegas, Pahrump, Jean, Mesquite, and locations within about 100 miles of Las Vegas as service areas.
Conclusion
Choosing the right concrete coating or finish starts with understanding the surface, how the area will be used, and the desired appearance and maintenance requirements. From garage floors and commercial spaces to patios and pool decks, proper preparation and suitable materials help support a durable, functional result. Performance Coating offers Las Vegas-area property owners a range of coating, polishing, restoration, and decorative concrete services to consider for their projects.
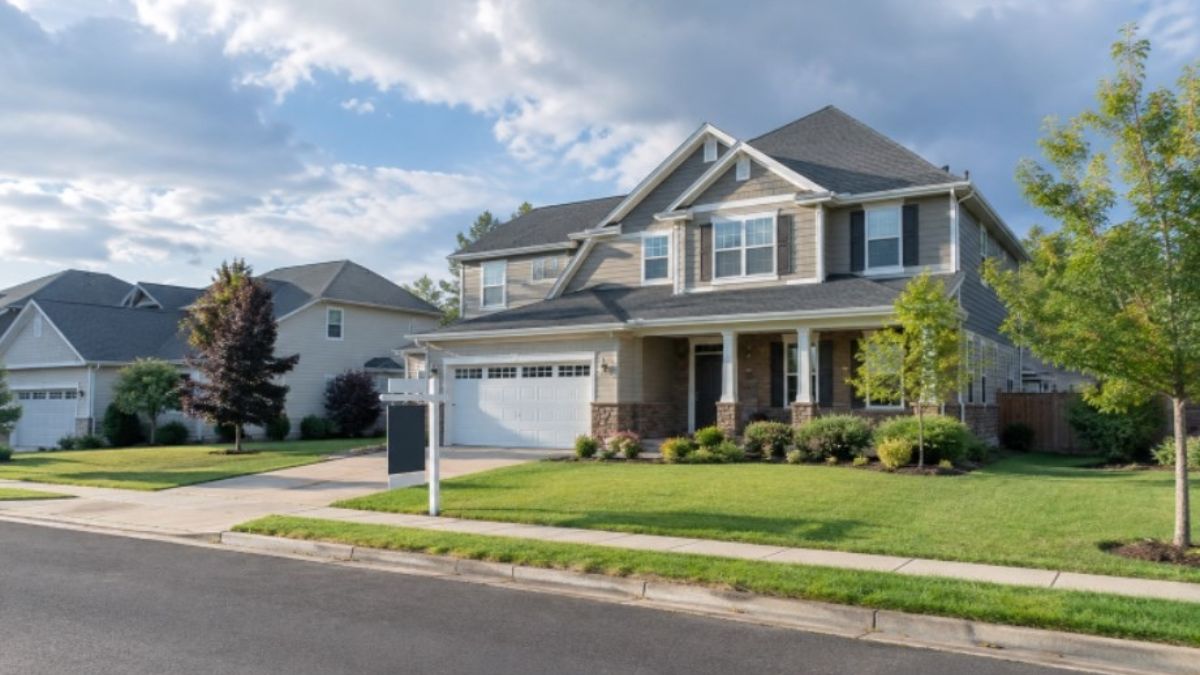
Selling a home is not only about choosing the highest number written on an offer. The right path depends on your property’s condition, your moving deadline, your financial needs, and the amount of uncertainty you are willing to accept. Homeowners considering companies that we buy houses often want a simpler sale, but convenience should still be weighed against likely proceeds and contract terms.
A cash sale and a traditional listing can both be legitimate options. The better choice is the one that gives you an acceptable net amount, a workable closing date, and terms you understand before signing.
What a Cash Home Offer Really Means
A cash offer generally means the buyer does not need a new mortgage loan to purchase the home. That can remove lender underwriting and appraisal requirements tied to financing, although a buyer may still request inspections, title review, or a short due-diligence period. Cash does not automatically mean the offer is higher, fairer, or guaranteed to close.
Sellers may consider a direct cash offer when they need a flexible closing date, want to avoid frequent showings, own a property needing substantial work, or prefer to sell as-is. The important question is whether the written offer reflects terms you can live with, not simply whether the buyer calls it cash.
How a Traditional Sale Works
A traditional sale usually involves preparing the home, setting a list price, marketing it to buyers, scheduling showings, reviewing offers, and negotiating inspections and closing details. The buyer may use a mortgage, which can introduce financing and appraisal contingencies before closing.
Listing a home can provide exposure to more potential buyers. In a favorable local market, broader exposure may create competing offers and improve negotiating leverage. However, this approach often requires more preparation, coordination, and patience as the transaction moves through inspections, appraisal, loan approval, title work, and settlement.
Why the Highest Price May Not Be the Best Deal
The offer price is not the same as your net proceeds. Net proceeds are the amount left after the costs and credits you agree to pay. Review expected repair expenses, cleaning, agent compensation or service fees, seller concessions, title and settlement charges, moving costs, and the cost of owning the home until closing.
For example, imagine a traditional buyer offers $400,000, but you expect $18,000 in repairs and preparation, $24,000 in selling-related fees and concessions, and $8,000 in additional mortgage, tax, insurance, and utility costs before closing. That leaves an estimated $350,000 before any other deductions. A $360,000 cash offer with lower selling costs could produce a similar or better result, even though its headline price is lower.
Benefits and Trade-Offs of a Cash Sale
Potential Benefits
- Closing may be scheduled more quickly because mortgage approval is not part of the transaction.
- There is typically less risk of a lender declining the buyer’s loan.
- Buyers may accept the property in its current condition, reducing upfront repair work.
- You may avoid open houses, repeated showings, and extensive staging.
- A direct buyer may offer more flexibility around possession or the closing date.
Potential Trade-Offs
- The offer may account for repairs, resale risk, holding costs, and the buyer’s desired margin.
- You may receive fewer competing offers than with a broad-market listing.
- An inspection or cancellation clause can give the buyer an opportunity to renegotiate.
- Administrative fees, assignment rights, or unclear deductions can change the amount you receive.
Benefits and Trade-Offs of a Traditional Sale
Possible Benefits
- A listing can reach buyers with different budgets, financing types, and reasons for purchasing.
- Multiple interested buyers may strengthen your position during negotiations.
- A market-ready home may appeal to buyers willing to pay for its condition, location, and features.
- You can test market response and adjust your strategy if needed.
Possible Trade-Offs
- Cleaning, repairs, photography, staging, and landscaping can require upfront spending.
- Showings may disrupt work, family routines, pets, or tenants.
- Financing, appraisal, inspection, and buyer contingency issues can delay or end a deal.
- The final negotiated price can differ from the original list price.
A Side-by-Side Comparison
- Closing speed: A cash sale may close sooner, whereas a traditional sale often involves more steps and third parties.
- Property condition: A cash buyer may accept an as-is property, while a traditional listing may benefit from repairs and presentation.
- Buyer competition: A direct offer typically involves a single buyer, whereas a listing can provide broader exposure.
- Financing risk: Cash offers generally avoid the risk of mortgage approval, but all buyers should still be verified.
- Convenience: A direct sale can reduce showings and preparation, while a listing usually requires more active participation.
- Potential price: A traditional sale may benefit from competition, while a cash offer may reflect speed and convenience.
Questions to Ask Before Accepting an Offer
- Who is the actual buyer, and what entity will appear on the contract?
- Can the buyer provide current proof of funds?
- Does the contract allow the buyer to assign the agreement to someone else?
- What inspection, financing, or cancellation rights does the buyer have?
- Which party pays title, escrow, transfer, recording, and settlement charges?
- Are repair credits, service fees, or other deductions listed clearly?
- What happens if the buyer does not close on the agreed date?
- Will the earnest money be held by a neutral title company or an escrow company?
Closing charges can vary by contract and location, so review the proposed settlement statement carefully. The Consumer Financial Protection Bureau’s common closing fees and charges show why sellers should ask exactly which expenses they will be expected to cover.
Warning Signs to Watch For
Slow down if a buyer pressures you to sign immediately, will not identify the purchaser clearly, refuses to provide written terms, or asks you to transfer ownership before payment is secured. The FTC warns that home-related scams can involve misleading promises, deed transfers, and requests for money or personal information, so review warning signs of home-selling scams before moving forward with an unusual proposal.
- Verbal promises that do not appear in the written contract
- Missing or questionable proof of funds
- Requests for payment through unusual methods
- Unexplained last-minute price reductions
- Pressure to avoid a title company, attorney, or other independent review
How to Choose the Better Option
A cash sale may be a practical fit if you have a firm deadline, cannot take on repairs, or want fewer moving parts. A traditional sale may fit better if the home is ready for buyers, you have time to prepare it, and you want to seek wider market exposure.
Use This Five-Step Process
- Estimate a realistic market value using recent comparable sales and local professional input.
- Request every cash offer in writing, including fees, contingencies, and the proposed closing date.
- Calculate estimated net proceeds for each option rather than comparing price alone.
- Have a real estate attorney, agent, or qualified settlement professional review unclear contract terms.
- Select the option that best matches your financial needs, timeline, and comfort with risk.
Common Questions
Is a cash offer always lower than a traditional sale?
No. A cash offer may be lower when a buyer is taking on repairs or providing extra speed and convenience, but the difference depends on the home’s condition, local demand, and the full terms of each offer.
Should a seller get more than one offer?
When practical, comparing multiple written offers can help you judge whether the price and terms are competitive. Focus on net proceeds, contingencies, deposit amount, closing date, and cancellation rights.
Conclusion
There is no single best way to sell a home in 2026. A cash offer can provide simplicity and speed, while a traditional sale can offer wider exposure and possible competition. Compare realistic net proceeds, contract protections, timing, and personal priorities side by side before making your decision.
-
 BLOG1 year ago
hanime1: The Ultimate Destination for Anime Lovers
-
 Technology1 year ago
GLAADVoice.com: How You Can Get Involved and Make a Difference
-
 BLOG1 year ago
Imginn: The Ultimate Tool to View Instagram Content Anonymously
-
 BILLS1 year ago
Why Does My Instagram Reel Stop Getting Views After One Hour? How to Fix It?
-
 ENTERTAINMENT1 year ago
Crackstreams 2.0: The Future of Free Sports Streaming?
-
 BLOG1 year ago
ThisVid: What Makes It Stand Out in the World of Online Videos
-
 ENTERTAINMENT1 year ago
Sflix: How It’s Changing the Way We Watch Movies and TV Shows
-
 BLOG1 year ago
NHentai.nef: Understanding the Popular Hentai Archive